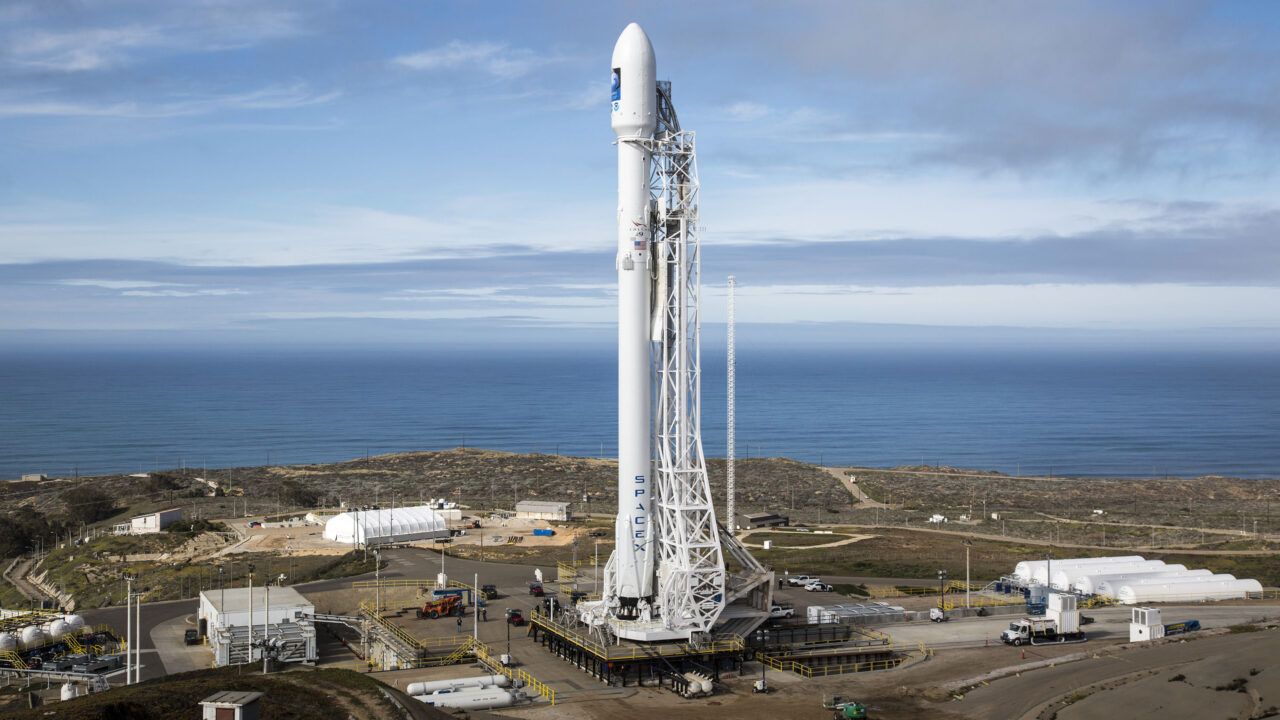
SpaceX is seeking about $40 billion in financing to buy Nvidia AI chips, the Financial Times reported on October 6, in a deal expected to be led by Apollo Global Management. Reuters, reporting the same day, said the Elon Musk-led company is looking to raise roughly $10 billion in bank loans and $30 billion in investment-grade debt for the chip order, citing people familiar with the matter.
The transaction is not expected to close until 2027. Pimco is among a small group of lenders in talks to provide financing, the reports said. SpaceX, Apollo and Nvidia did not immediately respond to requests for comment, while Pimco declined to comment. Shares in SpaceX fell about 1 percent in extended trading after the report, while Nvidia stock rose about 0.5 percent, a small market verdict on who benefits immediately from debt-funded chip demand.
The scale is striking even in context. Forty billion dollars is close to the company projected annual revenue, according to analyst estimates cited in coverage of the report. SpaceX went public in June in what was described as a record $86 billion initial offering, and sold $25 billion of high-grade bonds shortly afterwards. A further $40 billion raise would add substantially to the debt the company already carries, and analysts tracking the stock have warned about the trajectory of borrowing against the pace of capital spending.
The purpose is computing power. Musk has said his AI venture xAI, whose Colossus 2 data centre already runs hundreds of thousands of Nvidia processors, could more than double its chip count by December, and that SpaceX plans to use Nvidia hardware exclusively for its data centres. The reported financing would extend that strategy: buying processors outright, at scale, rather than renting capacity from cloud providers. In effect, a rocket company is assembling one of the largest private computing estates in the world, funded through the bond market.
Morgan Stanley has estimated that AI infrastructure will require $1.5 trillion in external financing by 2028, a figure quoted across this week reporting and one that frames the SpaceX talks as part of a pattern rather than an exception. Broadcom and Oracle are pursuing their own large chip financings through private credit. The common thread is that the cost of AI hardware has outgrown what even highly valued companies choose to fund from cash flow alone.
There are clear risks for lenders to price. AI processors depreciate quickly as new generations arrive, data centres take years to build and power, and the revenue that must service the debt depends on demand for AI services that is enormous today and unproven over the life of a long-dated bond. Against that, Nvidia chips are the closest thing the industry has to a standard asset, and contracted computing demand has so far outrun supply. The 2027 closing timetable gives both sides time to test which of those arguments ages better.
For now, the deal exists as reported talks, not signed documents, and its final size and terms may differ. But the direction of travel is unambiguous. The companies building the AI future are no longer just engineering organisations; they are becoming some of the largest borrowers in the world, and the chip at the centre of the boom is becoming collateral.
The financing would also test how far the boundary between space and computing has already moved. SpaceX absorbed xAI earlier this year, folding the AI venture into the same corporate structure as its launch and satellite businesses, and its data-centre ambitions now sit alongside rockets in the case it makes to investors. Bond buyers who once assessed launch cadence and satellite contracts are being asked to assess GPU fleets instead. That the conversation is happening at investment-grade scale, rather than in venture markets, says as much about 2026 as the headline number does.